Some links may be affiliate links. We may earn a small commission at no extra cost to you.
Information may change over time and should be verified with official providers. We are not responsible for any decisions made based on this content.
Pet Insurance That Covers Everything
Nothing can be covered under pet insurance. Comprehensive policies for accidents and diseases tend to cover only certain portions of veterinary costs. Actual reimbursement amounts vary depending on the deductible amount, reimbursement rate, annual limit, and exclusions.
The information provided by this article has been taken from industry resources as well as the publicly available policy documents. This will help pet owners understand the key coverage jargon before selecting a certain insurance plan.
- What Does “Full Coverage” Pet Insurance Actually Mean?
- What a Truly Comprehensive Pet Insurance Plan Covers
- How the 80% Reimbursement Rate Actually Works (Read This Before You Buy Anything)
- Important Coverage Gaps to Understand
- Annual vs. Per-Condition Deductible: The Math That Changes Everything
- Deep Research: How the Top Providers Compare on What Actually Matters
- The Premium Increase Reality
- Common Issues Pet Owners Should Watch For
- How Much Does Comprehensive Pet Insurance Actually Cost in 2026?
- Is Pet Insurance Worth It?
- When to Enroll: The Timing That Changes Everything
- Frequently Asked Questions
- The Bottom Line
What Does “Full Coverage” Pet Insurance Actually Mean?
No insurance policy for pets provides complete protection. In pet insurance terms, full protection stands for coverage against accidents and illnesses, with wellness benefits as optional coverage.
The best policy for you is influenced by your animal’s age, health, breed, location, and your money situation.
| Plan type | What it may cover | Best for |
|---|---|---|
| Accident-only | Eligible injuries such as fractures, foreign-body ingestion, lacerations, and poisoning | Owners seeking basic, lower-cost protection |
| Accident and illness | Accidents plus eligible illnesses such as cancer, diabetes, infections, and some hereditary conditions | Owners seeking broader medical coverage |
| Accident, illness, and wellness | Accident-and-illness care plus selected preventive services, such as vaccines and routine exams | Owners who want help with eligible preventive expenses |
Full coverage or comprehensive insurance means insurance that includes accident, illness, and optional wellness. This does not cover everything.
“Modern treatments like stem cell transplants or open-heart surgery are now possible, and having an insurance policy may influence whether some pet owners can pursue that treatment.”
Dr. Karen Halligan, DVM
Source: Money.com
What a Truly Comprehensive Pet Insurance Plan Covers
Insurance plans for accident and illness may help pay for emergency treatment, hospitalization, surgical procedures, diagnostic tests, and prescribed medications. Depending on the insurer and the plan, coverage may include hereditary and congenital conditions, kidney disease, behavioral therapy, holistic alternatives, exam costs, and prescription diet.
Not all policies cover these benefits. Some demand that customers pay for optional upgrades, apply limits, introduce waiting periods, or add exclusions. Policyholders should read the policy documents.
Benefits provided by some insurance companies include:
- Behavioral therapy and changes in behavior necessary for treatment.
- Veterinary exam costs.
- Prescription dietary solutions for cases requiring treatment.
- Dental care.
- Holistic solutions like acupuncture and rehabilitation.
- Implantation or similar processes.
Eligibility will depend on the insurance company or pet insurance, state regulations, condition being addressed, and policy details. Sample deductions and plans can be found in NerdWallet’s 2026 pet insurance section.
How the 80% Reimbursement Rate Actually Works
An 80% reimbursement rate does not necessarily mean the insurer will reimburse 80% of your total veterinary bill; policies guaranteeing 80% reimbursement will cover 80% of the complete veterinary bill. In reality, the reimbursement depends mostly on the types of costs that are eligible, the deductible, the limits of the policy, the exclusions, and the method of the claims calculation used by the insurer.
The Three Reimbursement Methods
Method 1: Percentage of Actual Vet Bill
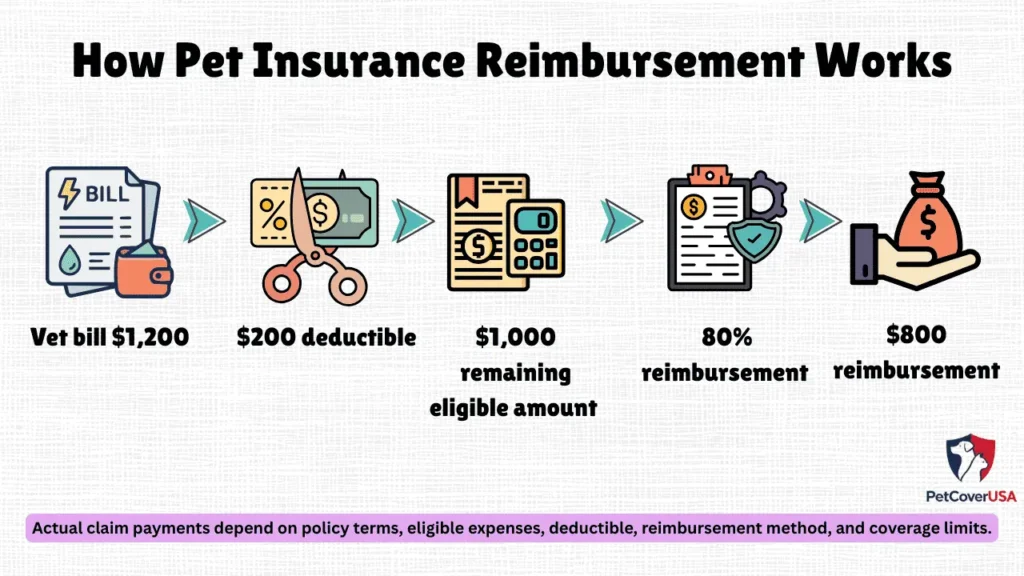
Some policies calculate reimbursement as a percentage of eligible veterinary charges after the deductible is applied. For example, if your eligible bill is $1,200, your annual deductible is $200, and your reimbursement rate is 80%, the insurer may calculate the claim this way:
- $1,200 − $200 deductible = $1,000.
- 80% of $1,000 = $800 reimbursement.
This example assumes the full bill is eligible and no additional limit or exclusion applies.
Method 2: Benefit Schedule
Some policies offer maximum amounts or set amounts for certain types of procedures done on the insured animal. If the insurer considers some amount smaller than what is charged by the veterinarian as eligible for the procedure, then the reimbursement will be based on the eligible amount rather than on the total bill.
For example, if the animal is treated for $800 but the insurer recognizes only $300 of this treatment as eligible, the insurer calculates the reimbursement based on $300 minus the deductible and the reimbursement percentage.
Method 3: “Reimbursement percentage Then Deductible” vs. “Deductible then reimbursement percentage”
Even in percentage-based plans, the order of calculation matters.
- Deductible first: From a $1,200 bill, subtract $200 → $1,000 left → 80% back = $800
- Copay first: From $1,200, take 80% = $960 → then subtract $200 → $760 back
That’s a $40 difference on a small bill — and $400+ on a $10,000 surgery.
Source: Embrace Pet Insurance reimbursement breakdown
My suggestion is to ask your insurance company, “Is reimbursement based on the vet fees I am entitled to, a benefits grid, or another method?” You should also ask them when they deduct your deductible. If they cannot describe their calculation very accurately, ask them to send the information in writing to make it easier for you to compare their policies with those of other insurance companies.
Important Coverage Gaps to Understand
This is important to understand carefully because this is where many pet owners may end up losing thousands of dollars over time.
Hidden Coverage Gaps That Can Affect Pet Insurance Claims
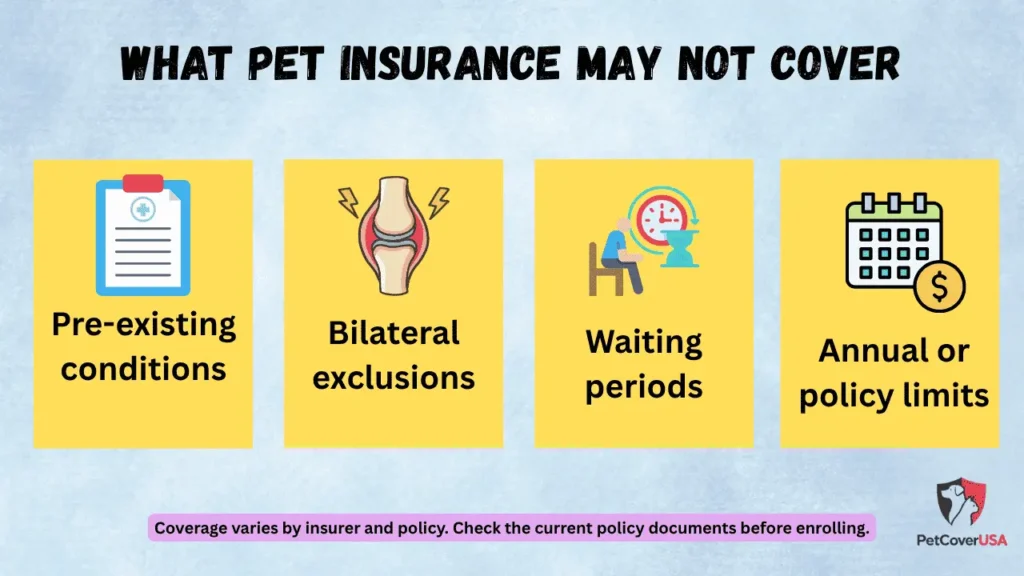
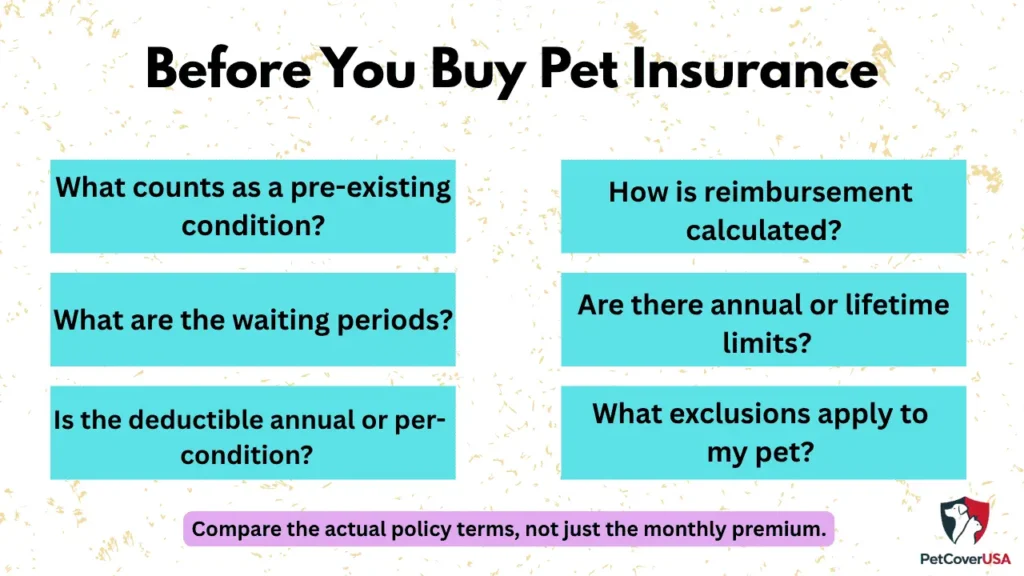
One important factor is what insurers consider a pre-existing condition. A condition may be considered pre-existing if signs or symptoms occurred before coverage began or during the applicable waiting period, depending on the insurer’s policy definition, whether or not the animal had been diagnosed. The particular wording in the insurer’s policy will determine this, as well as the relation of the prior symptom to the later claim.
For instance, if a veterinary note indicates that a dog had limped previously, the insurer will look at that history of the pet if it needs treatment later on for an orthopaedic issue. A vet note does not automatically prove that the subsequent condition is pre-existing but might prompt the insurer to ask for more details.
This is the reason for getting coverage even before symptoms start manifesting. Animal owners should examine their pet’s notes, learn the insurer’s policies regarding pre-existing conditions, and ask how it deals with temporary symptoms.
“Don’t wait until you have a problem to get insurance, get your pets examined when they are healthy. Once something is in a medical record, typically that leads to an exclusion in coverage.”
Dr. Sarah Gorman, DVM, CCRPManaging Veterinarian, Small Door Veterinary, New York
Source: AOL Finance / CNBC Select, November 2025
What you ought to do: If pet insurance is something that you wish to purchase, take time to compare insurance policies and enroll your pet as early as possible- ideally before the first visit to the vet or right after your pet comes home with you. Before signing up for a policy, check each policy for minimum age limits, effective dates, waiting periods, exclusions and pre-existing conditions requirements.
The Orthopedic Waiting Period
Certain pet insurance policy types can enforce longer waiting periods; some orthopedic issues, such as ACL injuries and hip dysplasia, can take months for coverage to begin. If you have a large-breed dog or a breed with known orthopedic risks, check the insurer’s waiting periods and exclusions carefully before enrolling; therefore, make sure you check the period of waiting time and exclusions, and pre-existing diseases, before signing up for the insurance policy.
The Annual Limit Exhaustion
A $5,000 annual limit may be used quickly if a pet requires extensive cancer treatment or another high-cost medical procedure. The unlimited annual cover is safer but comparatively more expensive and does not include excluded conditions.
Annual vs. Per-Condition Deductible: The Math That Changes Everything
Your choice of deductible will significantly impact how much money you spend on pet medical bills, particularly for pets with multiple conditions unrelated to each other.
Annual deductible ($250): In an annual deductible plan, you need to pay only one deductible within the policy term. After paying the deductible, you’ll be entitled to reimbursement of eligible claims as per the terms defined by the insurer.
Per-condition deductible ($250): In a per-condition deductible plan, a deductible needs to be paid for each eligible condition you are treating. To illustrate this, if you have an annual plan that requires you to pay a $250 deductible for every separate condition, and you have three different conditions during the year, the total deductible will add up to $750.
| Scenario | Annual Deductible ($250) | Per-Condition Deductible ($250) |
|---|---|---|
| One emergency, such as a broken leg | $250 deductible | $250 deductible |
| Three separate conditions in one year | $250 total annual deductible | Could be $750 |
| Recurring/chronic condition | Depends on policy terms | Depends on policy terms |
| Potentially more suitable for | Pets that may develop multiple conditions | Pets with fewer separate conditions |
Summary: It’s not always true that one kind of deductible is less costly than another. It would be best to compare how each insurance company applies different types of deductibles for new, recurring, and chronic conditions.
Deep Research: How the Top Providers Compare on What Actually Matters
| Feature | ASPCA Pet Health Insurance | Embrace | Trupanion |
|---|---|---|---|
| Reimbursement | Percentage of eligible veterinary expenses | Percentage of eligible veterinary expenses | Percentage of eligible veterinary expenses |
| Reimbursement options | Vary by plan and policy terms | Vary by plan and policy terms | Up to 90%, depending on policy terms |
| Deductible | Annual deductible options available | Annual deductible options available | Per-condition deductible |
| Annual limit | Selected limit or unlimited, depending on plan | Selected annual limit, depending on plan | No annual or lifetime payout limit, subject to policy terms |
| Orthopedic waiting period | Varies by policy and state | Varies by policy and state; waiver rules may apply | Varies by policy and state; applicable waiver rules may apply |
| Dental coverage | Varies by plan and policy terms | Limited or eligible dental coverage may be available | Eligible dental conditions, subject to policy terms |
| Behavioral treatment | May be available under certain plans | Coverage varies by plan | Coverage varies by policy |
| Exam-fee coverage | Varies by plan | May be available as optional coverage | Check applicable policy terms |
| Direct vet payment | Generally uses a reimbursement model | Generally uses a reimbursement model | Direct payment may be available at participating veterinary hospitals, subject to applicable rules |
| Hereditary conditions | May be covered if eligible and not pre-existing | May be covered if eligible and not pre-existing | May be covered if eligible and not pre-existing |
| Enrollment age | Varies by policy and state | Varies by policy and state | Varies by policy and state |
| Curable pre-existing conditions | Eligibility rules apply | Eligibility rules apply | Eligibility rules apply |
Note: Coverage, limits, waiting periods, deductibles, eligibility, and available options can vary by state and policy. Always review the insurer’s current policy documents before purchasing coverage.
The Premium Increase Reality
Due to multiple causes, pet-insurance premiums can shift upwards with time. Some causes are the age of the pet, general increases in the cost of veterinary care, and increases in premium costs by region and insurance company. Some insurance companies may take into account past claims made in determining premiums, while others claim that individual claims have no impact on the pricing of policy renewals. Carefully read all policy documentation before making decisions.
Some policyholders have reported excessive increases in their premiums when renewing policies, including a case when a Trupanion premium rose by 38% even though no claims had been made. Since the experience may vary, it would be wrong to take this incident as a generalized example. Source: nbcnews.com
Changing insurers when your pet has developed a condition can result in a lack of coverage, as a new insurance provider may refer to this condition as pre-existing. Before taking any actions, analyze the new policy’s terms.
Common Issues Pet Owners Should Watch For
Pattern 1: A Note Can Trigger Review
Some pet owners indicate that insurance providers had reviewed minor conditions that were recorded before coverage was issued when evaluating later claims. While a note indicating the presence of a limp or concerning walking could indicate a pre-existing condition in itself, it could also result in additional review or an exclusion. Resulting decisions concerning the claim could be made according to the wording of the policy and medical documentation itself.
Pattern 2: Claim Deadlines Matter
The deadline for filing a claim with a pet insurance provider may differ depending on the company and policy. While some providers will require that claims be submitted within a period of 90 days from the date of the pet’s treatment, others will require that claims be submitted within one year after the treatment. Before claiming, it is good to check the terms of the policy to see the deadline and documents that must be submitted in case you need to appeal.
Make sure to file the claim as soon as possible, as well as keep receipts and invoices. Failure to follow this process means that the claim could be denied or delayed based on the terms of the policy.
Pattern 3: Keep Your Own Paperwork
When filing claims with insurance companies, delays might occur as they have to wait for invoices or some other paperwork from the doctors. Ask for invoices with itemized services, keep copies of medical records, and keep everything in writing. This makes it easier to cope with requests regarding missing documents.
Avoid: “claims being denied constantly,” “each visit must always be claimed separately,” “even one day late means automatic denial,” and “no chance to appeal.” These statements are not universal and could reduce accuracy and trust.
How Much Does Comprehensive Pet Insurance Actually Cost in 2026?
According to Pawlicy Advisor’s examination of several quotes, the average cost of an accident-and-illness insurance policy for dogs is $62.44 per month and for cats $32.21. It is noted that monthly premium amounts for dogs have been recorded between $37.18 and $72.99 and for cats, $23.84 to $49.76.
It should be noted that these figures represent average costs and not guaranteed rates. Prices vary due to the dog’s breed, the dog’s age of a dog, the location of the insured pet, the insurance company chosen, deductible, reimbursement percentage, etc. The information provided by Pawlicy Advisor doesn’t claim to set an exact number for the insurance price for senior dogs aged 10 and older.
Veterinary treatment costs can vary from case to case, and the price of the treatment can go as low as zero or exceed $10,000. Therefore, one case of a surgical procedure must not be treated as final pricing for pets’ surgeries.
Source: Pawlicy.com
For example, if the quotation for the treatment is $3,000 and 80% of reimbursement under the policy is provided, the reimbursement will be equal to $2,400 (first considering any exclusions, deductible amounts, and annual limits specified in the policy).
Is Pet Insurance Worth It?
Pet insurance might be something to explore if you have a young and healthy pet, whether you will not be able to pay for a large emergency in cash, or whether you prefer certainty in your monthly budget. The situation is different in cases where an animal has severe health issues, you have a lot of money saved for emergencies, or if your goal is getting coverage solely for preventive treatment.
Based on a PetSmart Charities–Gallup survey, 52% of pet owners in the U.S. indicated that they had either skipped or even refused necessary veterinary assistance. Among these people, 71% said that money was their main concern. This shows why many people think about their insurance coverage and savings, but this does not mean that all expenses will be covered. Make sure that you know every detail about pre-existing-condition policies, waiting periods, deductibles, reimbursement percentages, exclusions, limits, and renewal options before you can get insured.
Source: AAHA.org
When to Enroll: The Timing That Changes Everything
The timing of enrollment is significant since conditions or diagnoses mentioned prior to enrolling or during a waiting period may be treated as pre-existing in accordance with the insurance policy. Insurance providers suggest taking out insurance when pets are young and have not developed any health problems, but there is no guarantee that the policy will cover all future health issues.
A Pawlicy Advisor study revealed that out of every 10 veterinarians, 9 are not happy to advise any particular pet insurance provider. However, it does not mean that the veterinarians are against using pet insurance; rather, it means that policies differ from one another and that there is no one suitable provider for all pets and households. Source: AAHA.org
Therefore, always compare definitions of pre-existing conditions, waiting periods, deductibles, reimbursement policies, exclusions, and maximum annual limits before enrolling. Getting insurance early helps reduce the number of pre-existing conditions that the insurance has to consider in a different way, but in general it all depends on the provider and policy.
Frequently Asked Questions
Some providers may consider limited coverage for certain curable conditions after a symptom-free period, but the rules vary. Conditions that showed signs before enrollment or during a waiting period are commonly excluded. Check the policy’s definition of a pre-existing condition before enrolling.
Coverage depends on the policy. Some plans may cover eligible dental illnesses, such as infections or certain extractions, while routine cleanings may require a wellness benefit or may not be covered. Check the policy’s dental exclusions, limits, and medical-necessity requirements.
Claim deadlines vary by insurer and policy. Some policies specify a certain number of days after treatment or after an invoice is issued. Review your policy documents so you do not rely on a general deadline that may not apply to your plan.
Renewal pricing can depend on factors such as your pet’s age, location, plan changes, underwriting rules, and veterinary-cost trends. A single claim may not be the only factor considered. Check the insurer’s renewal and pricing terms for more information.
You can usually apply to switch providers, but the new insurer may treat conditions or symptoms that began before the new policy or during its waiting period as pre-existing. Switching may also create new waiting periods or exclusions, so compare the new terms before cancelling your existing policy.
Many accident-and-illness plans may cover eligible cancer treatment, such as surgery, chemotherapy, or specialist care, when the condition is not pre-existing and the treatment meets the policy requirements. Coverage, exclusions, limits, deductibles, and reimbursement rules vary by insurer.
The Bottom Line
A full coverage pet insurance policy may not be readily available. However, a comprehensive accident-and-illness policy may cover many veterinary costs when it includes a high or unlimited annual limit, eligible veterinary expenditure reimbursement, and a yearly deductible. Coverage options are insurer- and policy-dependent.
When comparing various plans, you should look for the following aspects:
Timing of enrollment: If you enroll before any serious animal condition develops, it may allow you to minimize the number of pre-existing conditions the insurer must consider. But coverage may not be guaranteed.
Annual limits: Check the limits provided in the policies and see how they correspond to serious medical issues. The limit of $5,000 may be sufficient for one medical situation but not enough for another.
Reimbursement method: Ask if the reimbursement is made based on the actual bill from your veterinarian or the benefit schedule, and learn how deductibles and limitations are going to be applied and to what extent.
Policy details: Find out definitions of pre-existing conditions, waiting periods for orthopedic disorders, annual limits, reimbursement rules, and deadlines for filing claims.
Related Pet Insurance Guides
If you’re comparing comprehensive coverage options, our guide to affordable pet insurance plans for dogs and cats can help you balance coverage with your budget.
Provider-specific research can also help when comparing policies. Read our Lemonade pet insurance review to examine another major provider.
You can also compare another major provider in our Embrace pet insurance review .
If your dog is older, coverage needs may be different. See our guide to pet insurance for senior dogs over 10 years old for age-related considerations.
One important limitation to understand before buying any policy is how insurers handle existing conditions. See our guide to pre-existing conditions and pet insurance .
📅 Last Updated:
About the Author
M. Nouman is an independent researcher and writer focused on U.S. pet insurance. He reviews insurer policy documents, coverage terms, waiting periods, reimbursement options, exclusions, and publicly available veterinary and regulatory resources to create clear, research-based guides. His goal is to simplify complex insurance information so pet owners can make informed decisions based on reliable sources rather than marketing claims. Articles are reviewed and updated as policies and industry information change.
Areas of Research: Pet Insurance Policies, Coverage Analysis, Policy Comparisons, Waiting Periods, Reimbursement Models, Policy Exclusions, Claims Education